Picture this: you just closed out a strong year. Sales were up, the bank balance looks healthier than it has in a while, and you’re feeling good — until your accountant calls in March with a number you weren’t expecting. Suddenly a chunk of that “healthy” bank balance has to go straight to the IRS, and it’s money you’d already mentally spent on payroll, inventory, or just breathing room. If that’s ever happened to you, you’re not alone — and it’s usually not an income problem. It’s an envelope problem.
Sales Tax vs. Income Tax: Two Very Different Buckets
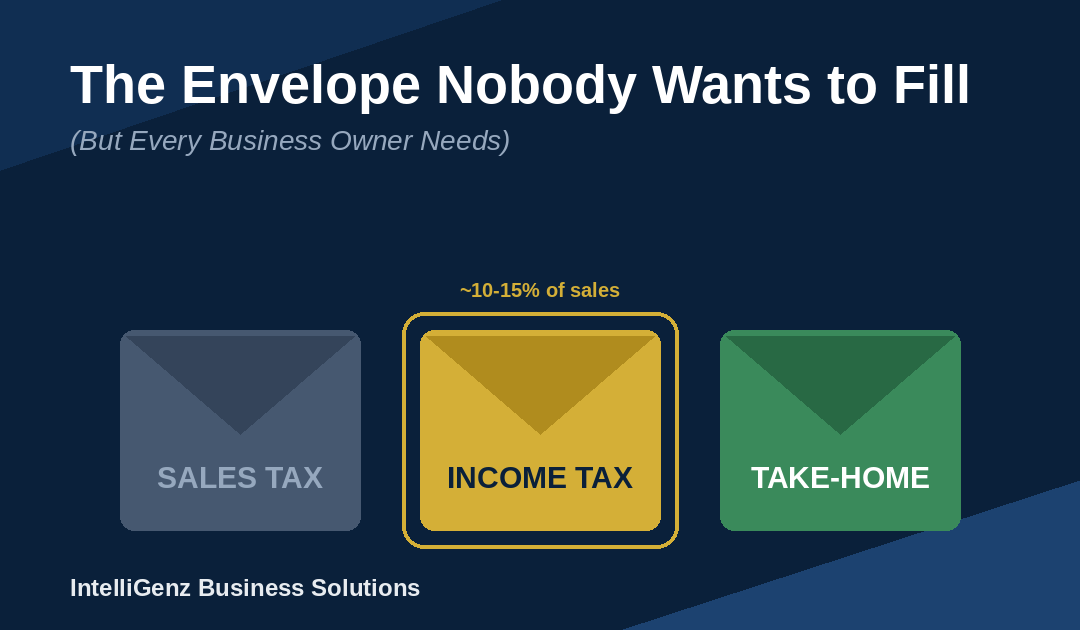
Most retail and restaurant owners already know, at least in theory, that sales tax collected isn’t really their money — it’s the state’s money, just passing through their bank account until it’s remitted, typically as a percentage of every sale. Income tax works on the same logic, even though technically it’s based on profit rather than revenue: if you set aside a portion of every sales dollar the same way you already do for sales tax, you’ll build up a cash cushion well before you actually owe anything — instead of scrambling to find it in April.
A Rough Way to Estimate Your Envelope
You don’t need exact numbers to get started — just a reasonable estimate you can adjust later. A simple rule of thumb: set aside roughly 10-15% of your total sales (not net profit — the goal here is a simple, consistent habit, not year-end precision) into an income tax envelope, adjusting up or down based on your typical margins, business structure, and state. If you’re doing $40,000 in sales for the month, that’s $4,000-$6,000 moved into its own account — not left mixed in with the money you’re using for payroll and vendor bills. It won’t land on the exact number you owe, and it doesn’t need to; the point is making sure the money’s there when it’s due instead of already spent.
Why This Is Worth Doing Even If You Hate Bookkeeping
The owners who get blindsided at tax time aren’t usually the ones with bad businesses — they’re the ones whose bank balance and their real cash position have quietly drifted apart. An envelope (literal, or more realistically, a separate savings account you don’t touch) keeps that gap from happening in the first place. It also makes tax season a lot less stressful, because the money’s already there instead of being a surprise bill you have to scramble to cover.
There’s another shift that happens once this becomes a habit: you stop dreading a good year. A lot of owners spend December looking for ways to “show no profit” — buying equipment they don’t need yet, prepaying expenses, anything to keep the number on paper low — because a big profit only feels like a big, unfunded tax bill waiting to happen. Once the government’s share is already sitting in its own envelope, a healthy profit stops being something to hide from. It’s just good news.
What to Do This Week
Open a separate savings account if you don’t already have one earmarked for taxes, and set up an automatic transfer of a rough percentage of your sales — the same way you’d hopefully already do with sales tax. It doesn’t have to be perfect on day one. It just has to exist.
This is exactly the kind of gap our Business Vitals Coaching℠ program is built to catch — not just whether you’re profitable on paper, but whether your cash is actually organized to support that profit. If tax time has ever felt like an ambush instead of a known number, let’s talk about getting your envelopes in order before it happens again.